


We had Laferla health insurance for roughly our first four years living in Malta. It was not the result of us sitting down and comparing every insurer when we first arrived. The relocation lawyers helping us move to Malta recommended Laferla, so we went with it and then simply kept renewing.
Fortunately, we never made a claim.
For normal healthcare, we have generally just paid ourselves. Private doctor appointments in Malta have been cheap and easy enough to arrange that filling in a reimbursement form for a small bill never seemed worth the trouble.
This year we finally compared the market properly. We obtained quotes from Atlas, GasanMamo, MAPFRE and Laferla, and went through the current benefit tables and policy documents rather than comparing the headline premiums alone.
The main thing we learned is that there are really two decisions to make: how well you want to be protected against a large private hospital bill, and whether you also want the insurer to pay for ordinary specialists and diagnostic work along the way.
For us, the first one matters much more.
How We Compared Malta Health Insurance Plans: Atlas, GasanMamo, MAPFRE and Laferla
The prices below are quotes we obtained in September 2026 for two Malta residents aged 37 and 42. We compared the current insurer benefit tables and policy documents as well as the quote and purchase process. They are our prices and may be different for you depending on age, medical history, underwriting and the cover selected.
Private Healthcare in Malta: GP and Specialist Costs at St James Hospital
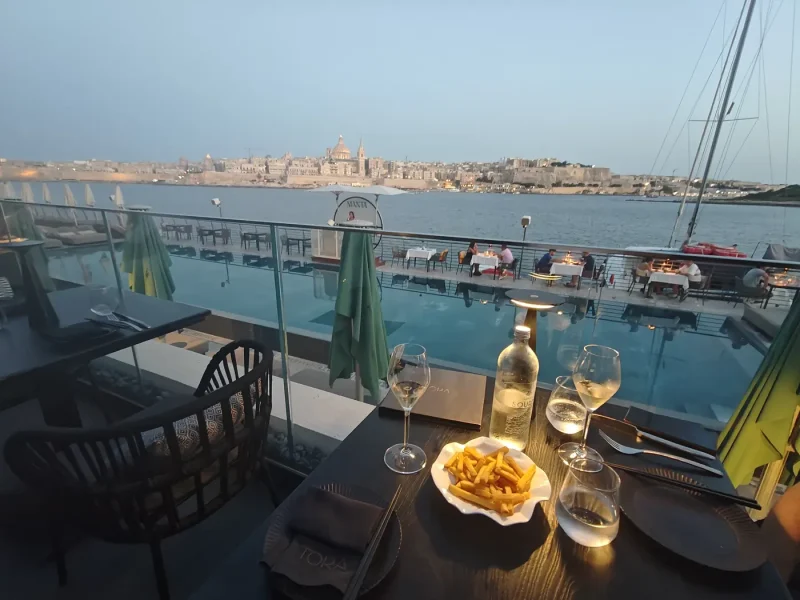
Most of our own private healthcare experience has been with St James Hospital.
A GP appointment has generally cost us around €25, while the specialists we have seen have usually been around €45. We have found it quite easy to get an appointment, often on the same day or the following day.
GPs are also available in plenty of other places around Malta, including practices attached to or operating alongside pharmacies, so an ordinary doctor’s appointment does not necessarily mean going to a hospital.
All the doctors we have personally seen have spoken English. They have been a mix of Maltese and international doctors, including British and Spanish doctors.
At those prices, we never bothered making a claim under our Laferla policy. We simply paid the bill ourselves.
That experience shaped this comparison. We are quite happy to pay €25 for a GP or €45 for an occasional specialist. What we actually want insurance for is the point where the bill stops being routine: hospital treatment, surgery, expensive scans or cancer care.
How Much Does Private Health Insurance Cost in Malta? Our 2026 Quotes
There was a surprisingly large spread once we compared plans with different levels of cover.
| Plan | Annual price for both | Broad type of cover |
|---|---|---|
| Atlas Private Hospital Value Plus | €649.10 | Strong hospital cover + selected outpatient treatment |
| GasanMamo In-Patient Key | €665 | Strong hospital cover |
| MAPFRE Basic | €705 | Limited inpatient + outpatient cover |
| GasanMamo Key | €1,140 | Strong hospital + broad outpatient cover |
| Atlas Private Hospital Full | €1,161 quoted | Strong hospital + broad outpatient cover |
| Laferla Silver | €1,425 | Strong Malta inpatient + limited outpatient cover |
| MAPFRE Hospital In & Out | €1,442 | Strong hospital + broad outpatient cover |
Atlas initially quoted us €678 for Value Plus. At checkout, a 5% online discount was applied and a €5 charge added, leaving €649.10 to pay.
For us, the market effectively separated into two price levels.
At around €650–€700 a year for both of us, we could insure the expensive hospital risk and continue paying much of the ordinary outpatient care ourselves.
At around €1,100–€1,450, we could also insure much more of the outpatient process: specialists, investigations and diagnostics before hospital treatment is needed.
Cheapest Health Insurance in Malta: Why Benefit Limits Matter More Than Price
The annual policy maximum can be misleading if you look at it without the individual benefit limits.
MAPFRE Basic, for example, has a €250,000 overall maximum, but hospital accommodation is limited to €185 per night for five nights. Theatre costs have separate limits, inpatient specialist and diagnostic treatment is capped at €325 a year, and cancer treatment is limited to €1,000 per course.
GasanMamo Vital follows a similar model, with limits such as €200 a night for hospital accommodation and €400 for a major theatre fee.
Those plans may be perfectly reasonable if you want a basic contribution towards private treatment.
They are less suited to what we are trying to insure. We are happy to absorb the small medical bills ourselves. We would rather transfer as much of the genuinely expensive hospital risk as possible.
Atlas Value Plus vs GasanMamo In-Patient Key: Best Hospital Cover in Malta
These became the two most interesting lower-cost options for us.
Atlas Private Hospital Value Plus: €649
Atlas Value Plus has a €600,000 annual maximum and provides full settlement of charges accepted by Atlas at supporting Malta hospitals for major inpatient and day-care treatment, including hospital accommodation, theatre fees, surgeons and anaesthetists.
What makes it particularly interesting is that it is not completely stripped of outpatient cover.
Atlas includes eligible outpatient surgical procedures, full settlement for specialist-referred MRI and CT scans and up to €150 a year for GP treatment. Atlas itself describes Value Plus as a lower-cost version of its Private Hospital cover that keeps the important inpatient benefits plus some expensive outpatient treatment.
That suits the way we currently use healthcare quite well.
The main compromise is ordinary outpatient specialist and diagnostic care. If a problem develops through several specialist appointments, blood tests, ultrasounds and follow-ups before anybody decides hospital treatment is necessary, more of those costs may still be ours.
Atlas also uses moratorium underwriting for Value Plus rather than asking for a complete medical history when you buy it. That makes the application simple, but pre-existing symptoms and conditions are initially excluded according to the moratorium rules.
GasanMamo In-Patient Key: €665
GasanMamo’s closest equivalent cost us only about €16 more. In-Patient Key has a €750,000 annual maximum per person and covers hospital accommodation, theatre costs, surgeons, anaesthetists and physician charges in Malta at approved-fee levels.
Inpatient specialists and diagnostics are also covered, while cancer treatment includes chemotherapy, radiotherapy, consultant fees, drugs and relevant imaging in Malta at approved-fee levels.
For our purposes, Atlas Value Plus and GasanMamo In-Patient Key are very close.
GasanMamo has the higher annual maximum. Atlas retains a few useful outpatient benefits, making it slightly more flexible. At this level, those details are more important to us than a €16 difference in premium.
There is also a caveat with both: terms such as full settlement or full approved fees do not mean that any bill from any provider will automatically be paid in full. Atlas refers to charges it accepts at supporting hospitals, whereas GasanMamo uses participating providers and an approved fee structure.
Full Outpatient Cover in Malta: Is It Worth €450–€500 More a Year?
This is probably the main decision for us.
GasanMamo Key: €1,140
The full GasanMamo Key plan retains the €750,000 annual maximum but adds much broader outpatient treatment.
GPs, specialist consultations, pathology, radiology, and diagnostic procedures in Malta are covered at approved fee levels. Specialist-referred MRI, CT and PET scans are also included.
There is also up to €750 a year for outpatient psychiatric treatment and €600 for emergency dental treatment following an accident.
The difference between €665 for In-Patient Key and €1,140 for full Key is therefore fairly easy to understand.
You are not mainly paying another €475 for better insurance once you are admitted to hospital. The cheaper Key plan already does that part well.
You are paying to insure much more of the investigation and outpatient treatment that happens before and outside hospital.
Atlas Private Hospital Full: €1,161
Atlas quoted us €1,161, only €21 more than GasanMamo Key.
Its Private Hospital plan has a €750,000 annual maximum, full settlement of accepted charges in supporting Malta hospitals and broad outpatient benefits under the full-cover version. Atlas’s current health pages distinguish this from Value Plus, where ordinary specialist outpatient treatment is removed but the major hospital benefits are retained.
At €1,140 versus €1,161, the premium would not decide this for us.
If we chose full cover, we would look much more closely at underwriting, exclusions, provider access and how pre-authorisation works.
MAPFRE Malta Hospital In & Out Review: Strong Cover, Higher Price

MAPFRE Hospital In & Out came to €1,442 for both of us.
The cover itself looks strong. It is intended for medically necessary acute inpatient and outpatient treatment, has an annual maximum of €600k, and includes hospital treatment, specialists, diagnostics, scans, and cancer care.
We did not find anything obviously wrong with it.
For us, the problem was simply the value. It cost roughly €300 more than GasanMamo Key or Atlas Private Hospital Full, and we could not identify an obvious difference in the core Malta cover that justified paying that much more for our circumstances.
Laferla Silver Review: Our Health Insurance for Four Years
Laferla was the familiar option. Our relocation lawyers recommended it when we moved to Malta, and since then we’ve simply kept renewing. We never made a claim, so we cannot comment from personal experience on how Laferla handles reimbursements or a serious hospital case.
Our latest Silver Plan quote was €1,425 for both of us.
Silver has an overall annual maximum of €350,000 and provides strong inpatient cover in Malta, including hospital accommodation, theatre fees, surgeons, anaesthetists, and inpatient diagnostics.
The outpatient side is less generous. GP treatment, specialists, outpatient diagnostics, and physiotherapy share a €750 annual limit, while ordinary outpatient prescription drugs are not covered under Silver.
That had never bothered us much because we were already paying the smaller outpatient bills ourselves.
But once we compared €1,425 with €1,140 for GasanMamo Key and €1,161 for Atlas Private Hospital Full, continuing automatically with Laferla became harder to justify.
Laferla acts as the insurance agency for this health product, while MAPFRE Malta is the underlying insurer.
Chronic Conditions: What Malta Health Insurance Doesn’t Cover
This was one of the more important things we found in the policy documents. The local Malta plans we compared are primarily designed for acute conditions, rather than for long-term management of chronic illness.
GasanMamo explicitly excludes chronic medical conditions, while MAPFRE similarly excludes treatment and monitoring of chronic conditions.
Atlas explains the same basic distinction in its current FAQ: private medical insurance is primarily for acute conditions that are likely to respond to treatment, rather than for long-term, incurable illnesses.
That matters much more than whether the plan reimburses a GP visit.
If you develop something that requires medication and monitoring for many years, a local private insurance policy may not function like a comprehensive public healthcare system.
For us, that would be part of a much wider decision. If one of us developed a serious long-term condition, we would reassess what made most sense overall at the time, including where to live and how best to access ongoing care.
Someone intending to stay in Malta permanently regardless of future health might reasonably approach the decision differently.
Exclusions to Check: Sexual Health, Vaccinations and Mental Health
“Full outpatient cover” does not mean every possible healthcare expense is covered.
The policies we reviewed contain restrictions or exclusions around areas such as sexual health, contraception, preventive treatment and vaccinations. GasanMamo, for example, explicitly excludes sexually transmitted infections including HIV/AIDS and contraception under its standard wording.
Mental-health cover was somewhat better than we initially expected. GasanMamo Key includes up to €750 per year for outpatient psychiatric treatment, subject to its conditions and authorisation requirements.
The practical lesson for us was not to assume that a broad outpatient policy automatically covers STI screening, PrEP or PEP, contraception, HPV vaccination, routine health checks or long-term therapy. These are areas where we would check the precise wording or ask the insurer in writing before relying on the cover.
Does Malta Health Insurance Cover Treatment Abroad?
These policies can include overseas benefits, but they are primarily Malta health insurance rather than comprehensive international medical insurance.
GasanMamo Key, for example, provides full approved hospital accommodation in Malta, while outside Malta accommodation falls to €240 per night for a maximum of five nights.
Atlas similarly gives its strongest Private Hospital benefits at supporting hospitals in Malta, with limited benefits elsewhere.
We already have separate travel insurance, so we gave relatively little weight to overseas emergency cover.
If you want insurance that follows you between countries or pays for planned treatment abroad, international private medical insurance is a different comparison — see also our AXA Global Health and Genki reviews.
Do You Need Health Insurance for Malta Residency?
That depends on your residence status.
For example, EU nationals residing in Malta on an economically self-sufficient basis must show valid comprehensive sickness insurance covering Malta unless they have another qualifying healthcare entitlement such as an S1 or entitlement certificate.
Certain non-EU residence categories have a minimum insurance requirement of €100,000, including medical treatment and hospitalisation in Malta. The exact rules depend on the type of application.
So we would check the current Identità requirements for the residence category actually being used rather than relying on a generic statement that every expat needs exactly the same policy.
There is also a difference between having insurance that satisfies an administrative requirement and having insurance you are comfortable relying on when something serious happens.
Atlas, GasanMamo, MAPFRE or Laferla: Whose Policy Documents Are Clearest?
This mattered more than we expected.
GasanMamo was probably the easiest for us to research. Its separate Vital, In-Patient Vital, Key and In-Patient Key documents made it easy to see what disappeared as the premium came down.
MAPFRE’s product documents were also reasonably clear once we compared Basic with Hospital.
Atlas actually publishes quite a lot. Its downloads section includes 2026 plan benefit tables, summaries, and separate product information documents. We found the naming slightly less intuitive, particularly the distinction between Private Clinic Full Cover, Private Hospital Full and Value Plus, but the underlying information is there.
Laferla was the company we already knew, but we found it harder to get the same immediate overview of the different options from the material we had.
None of this tells us which insurer will best handle a difficult future claim.
A Note on Claims: What This Comparison Can’t Tell You
That limitation is worth stating clearly.
We had Laferla insurance for roughly four years but never made a claim at all. When we needed to see a GP or a specialist, we paid ourselves.
We also have no claims experience with Atlas, GasanMamo or MAPFRE.
So this is not a claims-handling review. It is based on our experience with private healthcare in Malta, our actual 2026 quotes, the buying process, and the current policy documents.
Fortunately, we have never needed to test any of these insurers with a serious medical claim. I guess that is the real test.
Best Health Insurance in Malta: What We Would Choose
For the way we currently use healthcare, the most interesting lower-cost options are Atlas Value Plus at €649.10 and GasanMamo In-Patient Key at €665.
Both allow us to keep paying small routine healthcare costs ourselves while insuring the much larger hospital risk. Atlas has some useful outpatient benefits; GasanMamo has the higher overall annual maximum.
If we wanted broader outpatient cover too, GasanMamo Key at €1,140 and Atlas Private Hospital Full at €1,161 would be the logical step up.
Someone who regularly sees specialists, needs frequent diagnostic tests or simply prefers not to pay outpatient bills themselves could easily get more value from one of those full plans.
For us, after several years of actually using private healthcare in Malta, the distinction has become fairly simple:
The insurance is there for when the healthcare stops being routine.
Comparing options beyond Malta? See our best digital nomad health insurance guide, or how Malta stacks up against Cyprus for tax and rent.